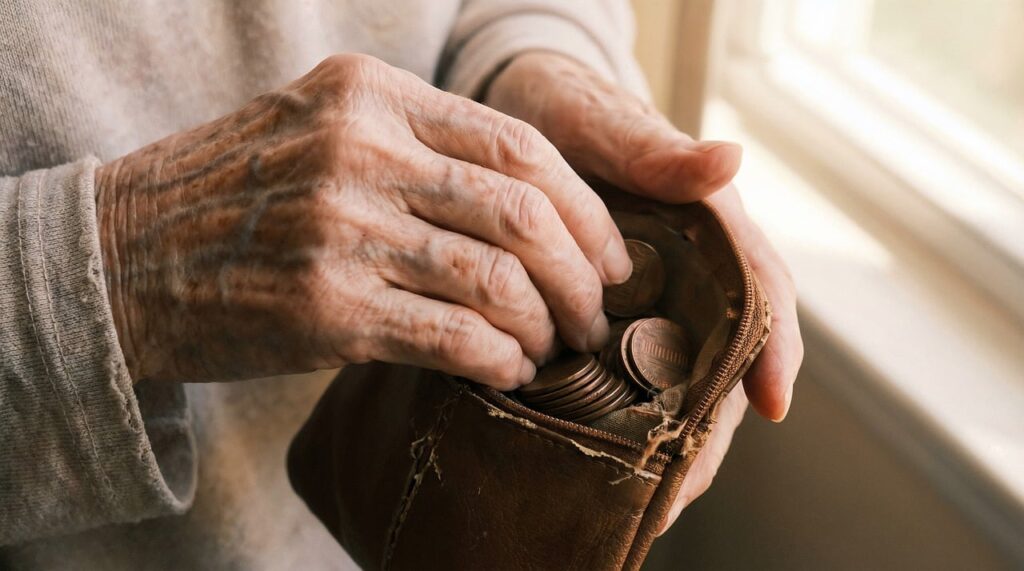
The UK government set out plans on Tuesday for a guided retirement scheme that gives private sector retirees a default option for income for life.
Providers Would Make Lifetime Income The Default
Ministers’ proposal, called Guided Retirement, gives retirees a default option designed to turn pension savings into income for life. The plans set out by pensions minister Torsten Bell require providers to offer an annual income as standard in retirement. The government describes the change as a guided scheme for private sector workers, intended to give savers a guaranteed income throughout retirement.¹²
The government says 17 million workers investing in a pension are affected; the plan specifically gives workers saving into a default pension the option of a DB guarantee. DB schemes provide a regular income for life after retirement, calculated from length of employment and salary. Over the past 30 years, the vast majority of private DB schemes that offered inflation-protected income have closed.¹²
Annuities Are No Longer Compulsory
The obligation to buy an annuity—an insurance product offering income for life—was scrapped, leaving many savers to decide how to manage their pension money. Annuities are no longer compulsory, but sales have been buoyant as returns for investors rose. Changes to inheritance tax rules have also encouraged wealthy people to move money out of pensions.¹²
The government says 17 million workers investing in a pension are affected; the plan specifically gives workers saving into a default pension the option of a DB guarantee.
 Government & Policy
UK Doubles Rough Sleeping Funding in England to £874 Million
New money extends support beyond March 2027, while outreach teams and added bedspaces are already operating in Coventry.
Read More →Auto-enrolment began in October 2012. Under the system, employers have to put every worker aged 22 and over into a pension scheme and make a company contribution. Workers can opt out, but nine in ten eligible private sector workers now contribute to a retirement fund, up from four in ten in 2012.¹²
Savers Keep Access To Withdrawals And Other Investments
Around 46 per cent of first-time pension pot accesses involved the entire pot being withdrawn in the 2025/26 tax years, according to the Department of Work and Pensions. That leaves some people at risk of entering retirement without enough funds or relying on the state pension. The government’s proposal responds to the challenge of turning pension savings into income that lasts.¹²
The guided option does not prevent people from withdrawing their money or investing it elsewhere. It gives them another route: a simple income option, with payments often linked to inflation. That feature would protect the value of payments as prices rise, while preserving access to other choices under the proposed regime.¹²
Pension Experts Warn About Preserving Choice
Bell said private sector workers deserved a better deal because too many people who save for retirement are left without a genuine pension when they reach it. He described the proposals as “resurrecting proper pensions” and said they guarantee the option of income throughout retirement, with protection against rising living costs in many cases.¹²
Yvonne Braun, director of long-term savings policy at the Association of British Insurers, said the proposed scheme could simplify decisions about accessing pensions. She also said people must retain the freedom to make their own decisions. Her concern addresses the balance between offering a default income and leaving savers in control of how they use their pension money.¹²
 Government & Policy
Gen Z in India Uses Labor Law Loopholes to Force Employers Into a Bargaining Arms Race
Generational expectations (Gen Z’s 41.7% labor force participation rate—down from Millennials’ 75%—forces firms to compete for a shrinking talent pool).
Read More →Steve Webb, pensions consultant at LCP and former pensions minister under the Coalition government, said managing a DC pot through market ups and downs without knowing how long it must last is challenging. He warned that the government could promote lifetime-income options too heavily, weakening pensioners’ freedom and choice over how and where to invest. People with secure income may prefer to take their DC savings in chunks when needed, he said, and he argued that a focus on retirement income must not destroy that flexibility.¹²
Pension Experts Warn About Preserving Choice Bell said private sector workers deserved a better deal because too many people who save for retirement are left without a genuine pension when they reach it.
Decide how you want your pension to pay out
If you are among the 17 million private sector workers saving into a default pension, the proposed guided retirement option gives you a new choice: a guaranteed income for life, often linked to inflation. This matters because most final salary schemes that once offered such protection have closed, leaving you to manage a defined contribution pot through market ups and downs. Before you decide, weigh whether you prefer a steady, inflation-protected income or the flexibility to withdraw your savings in chunks as needed, as former pensions minister Steve Webb notes.¹²
The data shows a real risk: nearly half of first-time pension pot accesses in 2025/26 involved the entire pot being withdrawn, which can leave you without enough funds in retirement. Under the guided regime, you keep the freedom to withdraw or invest elsewhere, but you also gain a simple default option. When planning, ask your provider about the annual income they must offer as standard and whether it protects against rising living costs. Also consider that annuity sales have been buoyant due to rising returns, so compare that route against the new default before committing.¹²
Sources
Written by Career Ahead AI. AI can make mistakes, so verify key facts. Report errors to support@careeraheadonline.com