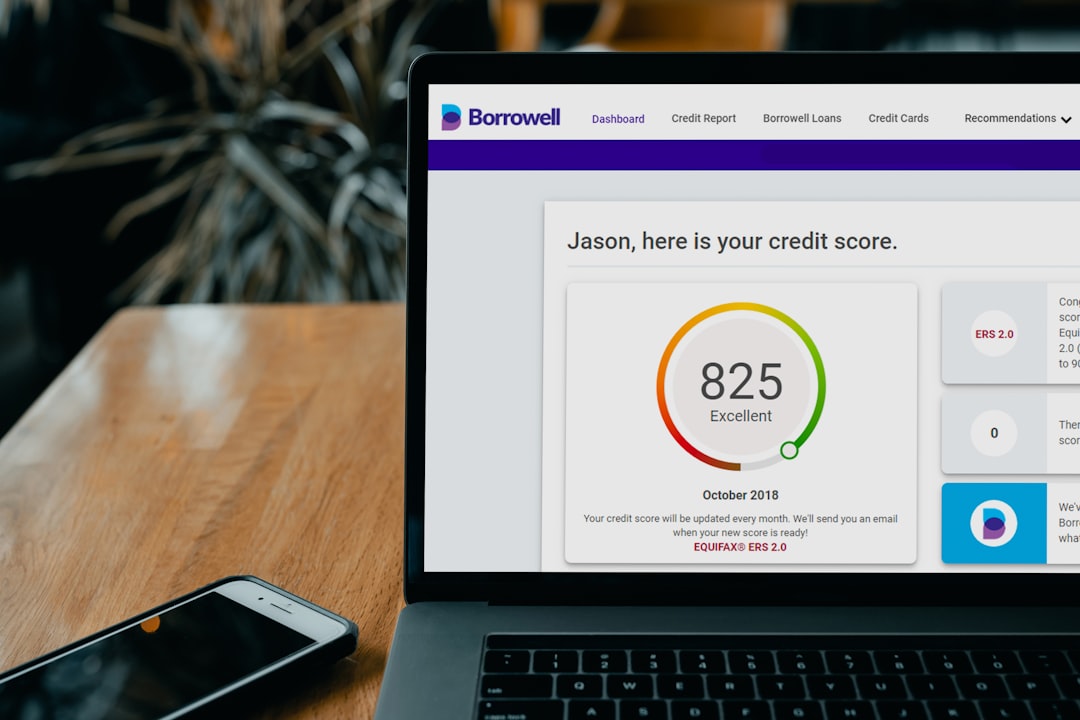
A 780 credit score may seem ideal, but various factors can lead to home loan rejection. Understanding what lenders evaluate beyond credit scores is essential for homebuyers and mortgage brokers alike.
India — A high credit score, such as 780, can significantly enhance a home loan application. However, it does not guarantee approval. Lenders consider a multitude of factors beyond credit scores when making lending decisions. Recent insights shed light on why even those with excellent credit can face rejection.
Homebuyers often express surprise when their mortgage applications are denied, despite boasting a strong credit score. This situation underscores the complexities of lending, where lenders assess various criteria to evaluate a borrower’s financial health. Understanding these factors is crucial for high-credit-score homebuyers and the mortgage brokers who assist them.
Understanding Lender Assessments
A credit score of 780 indicates a solid repayment history, but it is merely one component of a lender’s assessment. According to a recent analysis by Mint, lenders also evaluate income stability, existing financial commitments, and the overall debt-to-income ratio. This comprehensive evaluation helps lenders determine if a borrower can manage the loan amount requested.
For instance, if a borrower has high existing EMIs (Equated Monthly Installments) relative to their income, lenders may perceive them as a higher risk. The debt-to-income ratio is a critical metric that lenders analyze to assess repayment capacity. A high ratio may suggest that the borrower is over-leveraged, potentially leading to difficulties in meeting future financial obligations. Mint notes that lenders are increasingly cautious about borrowers who appear financially stretched, regardless of their credit score.
The Role of Employment History
Employment history plays a vital role in the approval process. Lenders prefer applicants with stable and consistent jobs, as this indicates reliable income. Frequent job changes or gaps in employment can raise concerns for lenders, prompting them to reconsider the application, even with a good credit score. According to Faster Capital, a solid employment history can enhance a borrower’s profile, while instability can create doubts about their ability to make consistent payments.
As of September 2026, rising interest rates are significantly impacting young professionals, particularly graduates burdened by student loans. This article explores the transition from manageable…
A high ratio may suggest that the borrower is over-leveraged, potentially leading to difficulties in meeting future financial obligations.
Career Ahead analysis reveals that lenders focus more on the borrower’s overall financial profile, including job stability and income consistency. For high-credit-score applicants, even minor discrepancies in income or employment can lead to rejection. Therefore, it is essential for borrowers to present a well-rounded financial picture when applying for a home loan. Lenders often require additional documentation to verify claims, complicating the approval process.
Importance of Documentation and Property Value
In addition to financial metrics, the quality and completeness of documentation can significantly impact approval chances. Lenders require thorough documentation to verify income, employment, and the property being financed. Incomplete or inaccurate documentation can result in delays or denials, even for applicants with high credit scores. Mint highlights that many applicants underestimate the importance of providing complete documentation, which may include tax returns, pay stubs, and proof of other income sources.
Moreover, the nature and value of the property are critical in the approval process. Lenders will assess whether the property meets their lending criteria and if its value justifies the loan amount. If the property has issues, such as being in a less desirable location or needing significant repairs, lenders may hesitate to approve the loan, regardless of the borrower’s credit score. The BBC notes that lenders are particularly cautious in fluctuating real estate markets, where property values can change rapidly. It is essential for borrowers to ensure their chosen property is a sound investment.
Preparing for Loan Applications
Given the multifaceted nature of loan assessments, homebuyers must recognize that a strong credit score is just the starting point. They should also focus on managing debt levels and maintaining stable employment to improve their loan eligibility. Mortgage brokers play a crucial role in educating clients about the factors affecting loan approval. By helping clients understand the importance of their overall financial profile, brokers can better prepare them for the lending process.
This preparation may include advising clients on improving their debt-to-income ratios or ensuring they have all necessary documentation ready before applying. As the lending landscape evolves, homebuyers with high credit scores should remain vigilant. The key takeaway is that while a high credit score is advantageous, it does not guarantee loan approval. Instead, it is one of many factors that lenders consider, highlighting the need for a comprehensive approach to financial health.
Moreover, the nature and value of the property are critical in the approval process.
Frequently Asked Questions
What factors can lead to mortgage rejection despite a high credit score?
High existing debt levels, inconsistent employment history, and incomplete documentation can lead to mortgage rejection, even with a high credit score. Lenders evaluate the overall financial profile, not just the credit score.
How can mortgage brokers better prepare clients for loan applications?
Mortgage brokers can prepare clients by educating them on the importance of a complete financial profile, including debt-to-income ratios and employment stability. Ensuring clients have all necessary documentation ready can also improve their chances of approval.
What should homebuyers do if their loan application is rejected?
If a loan application is rejected, homebuyers should review their financial profile and address any weaknesses, such as high debt levels or incomplete documentation. Consulting with a mortgage broker can provide valuable insights into improving future applications.



Career Tips
 Career Tips