No products in the cart.

Zimbabwe Central Bank Eyes NPCI Deal for Digital Payments
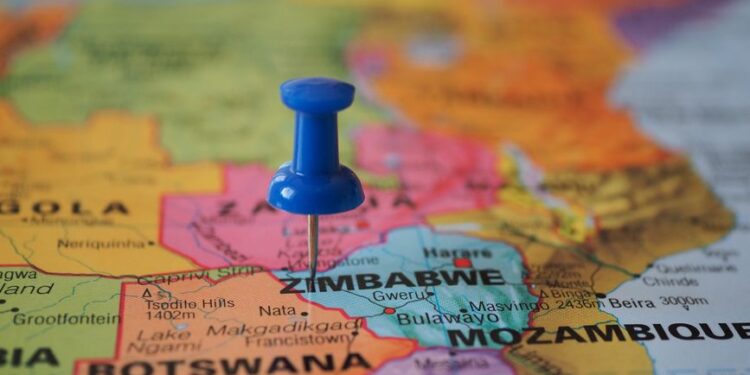
Zimbabwe's Central Bank is pursuing a partnership with India's NPCI to enhance digital payments, aiming to modernize banking infrastructure and improve financial inclusion. This collaboration could transform Zimbabwe's fintech landscape, drawing parallels with India's successful UPI system.

Zimbabwe’s Central Bank is actively seeking a partnership with India’s National Payments Corporation of India (NPCI) to enhance its digital payment systems. This initiative, announced in October 2026, aims to leverage NPCI’s technological expertise to modernize Zimbabwe’s banking infrastructure and improve financial inclusion across the country.
The collaboration with NPCI represents a strategic move for Zimbabwe as it looks to boost its digital payment capabilities. NPCI, known for its successful Unified Payments Interface (UPI) system, has been instrumental in transforming India’s digital finance landscape. By adopting similar technologies, Zimbabwe could significantly enhance its payment processing efficiency and security. According to a report by Bloomberg, NPCI’s systems have already proven effective in increasing transaction volumes and reducing costs in India, which could be replicated in Zimbabwe’s context.
Enhancing Digital Payment Solutions
Zimbabwe’s banking sector has faced numerous challenges, including a lack of reliable payment systems and limited access to digital financial services. The NPCI deal could address these issues by introducing robust digital payment solutions that facilitate seamless transactions. Career Ahead’s analysis finds that implementing NPCI’s technology could reduce transaction times and costs, making digital payments more accessible to the general population. Furthermore, the integration of NPCI’s technology could lead to the development of a more competitive banking environment, driving local banks to innovate and improve their service offerings.
With NPCI’s proven track record in India, the partnership could also foster innovation in Zimbabwe’s fintech sector. By integrating advanced technologies such as mobile payments and contactless transactions, local banks can offer improved services to customers. This shift not only enhances user experience but also positions Zimbabwe as a competitive player in the regional fintech landscape. As reported by BBC News, the potential for NPCI’s technology to streamline payment processes could lead to a significant uptick in digital transactions, further embedding digital finance into everyday life.
As banks adopt these new technologies, there will be a growing demand for skilled professionals in areas such as software development, cybersecurity, and data analytics.
Moreover, the NPCI collaboration is expected to create new job opportunities in the fintech sector. As banks adopt these new technologies, there will be a growing demand for skilled professionals in areas such as software development, cybersecurity, and data analytics. This influx of jobs can help mitigate unemployment rates, particularly among young graduates entering the job market. The rise of fintech startups, fueled by the NPCI partnership, could also contribute to economic diversification, reducing reliance on traditional sectors.
You may also like
 Industry & Global Trends
Gulf Attacks Escalate Tensions, Impacting Energy Trade Dynamics
Recent attacks in the Gulf have heightened concerns about energy trade stability, significantly affecting oil prices and supply chain logistics. This situation necessitates a reevaluation…
Read More →The potential for job creation extends beyond traditional banking roles. Fintech startups may emerge as a result of this partnership, driving further innovation and economic growth in Zimbabwe. By fostering a vibrant ecosystem for digital finance, the NPCI deal could lead to the establishment of new businesses focused on payment solutions, lending, and financial technology services. This entrepreneurial spirit is crucial for Zimbabwe, where economic challenges have necessitated a shift towards more sustainable and innovative business models.
Impact on Local Banking Infrastructure
The introduction of NPCI’s technology is likely to have a profound impact on Zimbabwe’s banking infrastructure. Currently, many banks in the country struggle with outdated systems that hinder their ability to provide efficient services. By adopting NPCI’s advanced payment systems, banks can modernize their operations and enhance customer satisfaction. The integration of these systems could also lead to improved interoperability among banks, allowing for smoother transactions across different financial institutions.
Furthermore, NPCI’s technology can improve the security of transactions, which is a critical concern for both consumers and financial institutions. Enhanced security measures can build trust among users, encouraging more people to engage with digital payment platforms. As trust in digital finance grows, the overall adoption rate of electronic payments is likely to increase. According to Bloomberg, the success of NPCI’s UPI in India has demonstrated that secure and efficient payment systems can significantly boost consumer confidence in digital transactions.
This could lead to the development of new products tailored to the needs of a tech-savvy population.
Career Ahead research identifies that this shift towards digitization is not just about technology but also about changing consumer behavior. As more individuals become comfortable with digital transactions, banks will need to adapt their services to meet evolving customer expectations. This could lead to the development of new products tailored to the needs of a tech-savvy population. Moreover, the NPCI collaboration can facilitate better integration with regional payment systems, promoting cross-border transactions. This is particularly significant for Zimbabwe, which relies on trade with neighboring countries. Improved payment systems can streamline trade processes, making it easier for businesses to engage in international commerce.
You may also like
 Industry & Global Trends
Engineering Students Shift Focus to Emerging Fields
The engineering landscape in India is undergoing a significant transformation as students increasingly opt for technology-driven disciplines over traditional branches. This shift reflects changing job…
Read More →Overall, the partnership with NPCI signals a transformative phase for Zimbabwe’s banking sector. By modernizing infrastructure and improving payment systems, the country can enhance its economic prospects and align itself with global financial trends. The anticipated improvements in payment efficiency and security could also attract foreign investment, further bolstering Zimbabwe’s economic recovery.
The NPCI deal presents numerous opportunities for Zimbabwe’s financial sector, but it also comes with challenges. As the country embarks on this digital transformation journey, stakeholders must address issues such as regulatory compliance, infrastructure development, and public awareness. Regulatory frameworks will need to evolve to accommodate new technologies and protect consumers. Ensuring that the legal landscape supports innovation while safeguarding users is crucial for the success of digital payment systems. This requires collaboration between the government, financial institutions, and technology providers.
Additionally, public awareness campaigns will be essential to educate consumers about the benefits of digital payments. Many individuals in Zimbabwe may still prefer cash transactions due to a lack of understanding of digital solutions. By promoting financial literacy and demonstrating the advantages of digital payments, adoption rates can increase significantly. As Zimbabwe moves forward with the NPCI partnership, monitoring the progress and impact of these changes will be vital. Stakeholders should remain vigilant about potential risks and adapt their strategies accordingly. The evolving landscape of digital finance presents both challenges and opportunities that can shape the future of Zimbabwe’s economy.
Ultimately, the collaboration with NPCI could mark a turning point in Zimbabwe’s approach to digital finance. As the country embraces new technologies, it will be interesting to see how this partnership influences the broader financial ecosystem and whether it can lead to sustainable economic growth.
As the country embraces new technologies, it will be interesting to see how this partnership influences the broader financial ecosystem and whether it can lead to sustainable economic growth.
Frequently Asked Questions
What are the benefits of NPCI’s technology for Zimbabwean banks?
NPCI’s technology can enhance transaction efficiency and security for Zimbabwean banks. By adopting systems like UPI, banks can modernize their services and improve customer satisfaction, ultimately leading to increased financial inclusion.
How can financial analysts leverage this NPCI deal in their reports?
Financial analysts can highlight the potential for job creation in the fintech sector and the impact on local banking infrastructure. They can also analyze trends in digital adoption and consumer behavior as a result of the NPCI partnership.
What steps should banking executives take to prepare for the NPCI partnership?
You may also like
 Industry & Global Trends
Super Rich Worth $160 Billion Exit UK
The trend has been exacerbated by various factors, including escalating taxes on wealth and property, prompting many high net worth individuals (HNWIs) to seek residence…
Read More →Banking executives should focus on understanding the technological implications of the NPCI deal and invest in training their staff. Additionally, they should collaborate with regulators to ensure compliance and explore innovative product offerings that cater to a digital-savvy customer base.