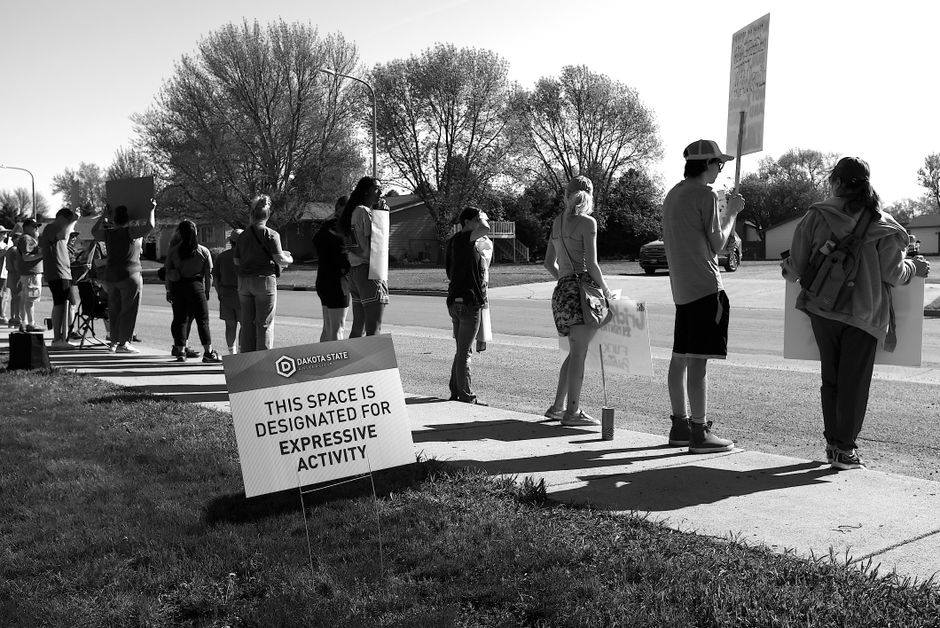
The Treasury Department and IRS proposed allowing officials to revoke private college tax exemptions for race or ethnicity discrimination.
The Rule Covers School-Run Programs Beyond Admissions
The proposal reaches the administration of educational and admissions policies, scholarship and loan programs, athletic programs, and any other school-administered or school-supported program. That places a wide range of school activities within its terms, not only decisions about who gets admitted. The rule does not define which campus activities count as school-administered or school-supported, a gap that became a central objection in comments from higher education groups.¹
The IRS said all forms of racial discrimination in education would violate a fundamental public policy of the United States and prevent a school from claiming a federal income-tax exemption, regardless of intent or legality. That includes conduct defended as serving remedial or diversity-related objectives. The agency also said race-based action intended to address societal or past racial discrimination would itself count as further discrimination.¹
Higher Education Groups Say the Terms Are Unclear
Ted Mitchell, president of the American Council on Education, submitted a roughly fifteen-page comment on behalf of his organization and forty other higher education groups. The coalition included the National Association of Independent Colleges and Universities and the American Association of University Professors. Its objections focused on how the IRS might apply the proposal to classroom teaching and activities beyond formal school policies.¹
The IRS said all forms of racial discrimination in education would violate a fundamental public policy of the United States and prevent a school from claiming a federal income-tax exemption, regardless of intent or legality.
 Education & University Insights
India’s Higher Education Agenda Puts Skills, Research and Faculty First
A panel framed the debate around India@2047, while a university chancellor said competitive research ecosystems can take 10–15 years to develop.
Read More →Mitchell wrote that contentious or even offensive classroom instruction on race or history could fall within the IRS’s broad definition of discrimination. He also said the proposal did not make clear which campus or student activities might qualify as school-administered or school-supported. Without those boundaries, colleges could have difficulty knowing which teaching choices or activities could put their tax status at risk.¹
Mitchell said the proposal appeared to leave the IRS entirely free to decide what conduct could be sanctioned. He called that lack of clarity constitutionally problematic under any scenario and especially concerning in light of the administration’s statements and overall course of conduct over the past twenty-one months. The comment’s concern is about both the breadth of the rule and the agency’s discretion to apply it.¹
Losing Exemption Could Affect Donations and Stability
A loss of federal income-tax exemption could make donors hesitate to give because they would no longer be able to write contributions off on their taxes. The National Association of College and University Business Officers said the change could severely undermine institutional financial stability. The proposal therefore carries consequences beyond a school’s own tax bill: it could also affect whether donors contribute and the financial support institutions receive.¹
The proposal is part of the administration’s effort to interpret more broadly a 2023 Supreme Court ruling that banned affirmative action in admissions. Since the return to the White House, federal agencies have cut off billions of dollars in research funding to selective private and public universities based on accusations of discrimination. Harvard University fought in court and won back its funding.¹
The IRS Cites a Case Involving Bob Jones University
As of publication time Tuesday, the final day for public comments, the agency had received nearly two thousand four hundred comments. Treasury Secretary Scott Bessent said in a news release in September that schools could not change the discriminatory nature of race-based preferences by describing them as equitable, inclusive, or diversity-enhancing. That position echoes the proposal’s treatment of remedial and diversity-related aims.¹
 Education & University Insights
BSC Kuwait Explores Rebrand After BSC Education Liquidation
The Kuwait centre was established as a locally registered legal entity and had an agreement to use BSC Education’s brand and course materials.
Read More →The IRS cited the 1983 case Bob Jones University v. United States. In an eight-to-one decision, the Supreme Court upheld the IRS’s revocation of the university’s exemption after it denied admission to applicants who engaged in an interracial marriage or were known to advocate for one. The court said a tax-exempt institution’s purpose must not conflict so sharply with the common community conscience that it undermines any public benefit. It also concluded that racial discrimination in education is contrary to public policy and that racially discriminatory educational institutions cannot be viewed as conferring a public benefit within the charitable concept or congressional intent.¹
The National Association of College and University Business Officers said the change could severely undermine institutional financial stability.
Check a college's tax risk before you enroll
If you are weighing private colleges, add tax-exemption stability to your list of questions. A school that loses its exemption could see donors pull back, since contributions would stop being tax-deductible, and that could shake its finances. Ask admissions or financial aid offices whether they have assessed this proposal's reach, especially its unclear definition of which campus activities count as school-supported.¹
For faculty or staff, the rule's vagueness is the real career risk. Classroom discussions on race or history could be treated as discrimination, and the IRS would decide what conduct is sanctionable. That means your teaching choices could put your employer's tax status at stake, so watch how your institution responds to this uncertainty before you accept a role or plan a course.¹
Sources
Written by Career Ahead AI. AI can make mistakes, so verify key facts. Report errors to support@careeraheadonline.com